All Categories
Featured

Effective Strategies for Fixing Poor Credit Quickly
Table of Contents
Revealing outcomes for "how" in what method or manner; by what ways?. How did the mishap occur? to what level, degree, etc?. How harmed is the automobile? in what state or condition?. How are you? for what factor; why?. How can you talk such rubbish? to what result; with what meaning?.
(utilized as an intensifier). How hardly ever I go there! How are the new cars and trucks going, more affordable than last year's models?
How does the devil appear in the first act of the opera? How does the medication come? I do not care how you leave your desk when you go.
In whatever manner or method;. You can take a trip how you please. He informed us how he was honest and might be relied on.
A Strategic Roadmap to Higher Credit Ratings
You haven't any desire to go? How come you never ever visit us anymore?/ ha/ Facetious: Frequently Offensive.
cricket (an attract the umpire) is the batsman out? archaic what is the meaning of this? :. not_standard that he informed me as how the shop was closed in whatever method do it how you want utilized in exclamations to highlight level how happy I was! (intensifier) extremely much so! (as a toast) health! "Collins English Dictionary Complete & Unabridged" 2012 Digital Edition William Collins Sons & Co.
1979, 1986 HarperCollins Publishers 1998, 2000, 2003, 2005, 2006, 2007, 2009, 2012 the way a thing is done the how of it "Collins English Dictionary Complete & Unabridged" 2012 Digital Edition William Collins Sons & Co. Ltd. 1979, 1986 HarperCollins Publishers 1998, 2000, 2003, 2005, 2006, 2007, 2009, 2012 a welcoming supposed to be or have actually been used by American Indians and often used humorously "Collins English Dictionary Total & Unabridged" 2012 Digital Edition William Collins Sons & Co.
1979, 1986 HarperCollins Publishers 1998, 2000, 2003, 2005, 2006, 2007, 2009, 2012 See firewater. First recorded before 900; Middle English hou, ou, hu, Old English h; cognate with Old Frisian h, ho, Dutch hoe; comparable to Old High German hweo, German wie, Gothic hwaiwa Very first recorded in 181020; of uncertain origin Examples are offered to show real-world use of words in context.
From Jul. 28, 2026 Warsh developed five task forces of outside professionals to examine the main bank analyzes the economy and interacts its decisions. From Jul. 28, 2026 However in his latest book, Levine shifts the focus from identifying accessory styles to ask a various concern: do you end up being protect? From "Phineas Gage" by John Fleischman Long Time 'SportsCenter' anchor Shae Cornette has been named the brand-new of 'Very first Take,' ESPN's popular sports argument reveal starring Stephen A. Smith.
8, 2025 The are simpler to describe than the whys when it concerns all this madness, so let's begin there. From Nov. 7, 2023 Physicists believe that there should have been some primitive imbalance that permitted matter to dominate deep space, yet the and whys remain open questions. From Sep.
From "American Street" by Ibi Zoboi Definitions and idiom meanings from Unabridged, based on the Random Home Unabridged Dictionary, Random Home, Inc. 2023 Idioms from The American Heritage Idioms Dictionary copyright 2002, 2001, 1995 by Houghton Mifflin Harcourt Publishing Business. Published by Houghton Mifflin Harcourt Publishing Business.
How did you like the motion picture!.?. !? She didn't say how far it is to her house. How long are you going to be at the health club!.?.!?" Hi, how are you?" "Fine, thanks, how are you?"( also How's whatever?);(How's it going?)" I'm Jack Stewart. "" How do you do, I'm Angela Black.". Different kinds of credit report designs might compute your score differently, but they normally consider payment history, amounts owed, length of credit history, brand-new credit, and credit mix. Using for excessive brand-new credit at the same time can momentarily reduce your score and might make lending institutions see you as a higher-risk borrower.
Examining your credit report frequently with the significant credit bureaus can help you capture errors, area possible identity theft, and disagreement inaccurate info. An excellent credit history can make it much easier to certify for credit and might help you improve rate of interest on significant purchases, such as a home or cars and truck.
Evaluating Credit Repair and Counseling Options
As a financial consultant, I've worked with a lot of individuals who've hurt their credit history in one way or another due to the fact that they didn't understand the basics. Fortunately is that credit history can frequently improve with constant routines gradually. Comprehending what impacts your score is the first step.
A credit rating is a mathematical expression of how credit-worthy you are. And a major consider that boils down to how likely you are to make your payments on time. It takes into account info from your credit report, including credit card business you've handled, banks where you have or previously had loans, and practically anybody else who's considered you for credit.
That's because, while there are a number of firms that produce credit ratings, FICO ratings are amongst the most widely utilized. They range from 300 to 850, and each variety figures out how likely you are to get credit and at what interest rate.
Various credit ratings like FICO or VantageScore use slightly various techniques to compute your rating. In general, your score is based on five factorshere are current FICO weightings: Your payment history (35%) How much you owe (30%) How long you have actually been utilizing credit (15%) Number of new credit accounts and applications (10%) Types of credit you use (10%) Comprehending how all this fits together is vital to addressing the next, possibly most important concern.
Navigating Credit Repair Laws in 2026
A bad credit score might be due to some mistakes you've made, or it might be due to the fact that you're new to the credit world and don't have much to reveal for it. Whatever the factor, here are seven things you can do to bring that score upand keep it there.
Making routine, on-time payments is one of the finest ways to bring it back up. That's what I did to enhance my own rating when I got out of college.
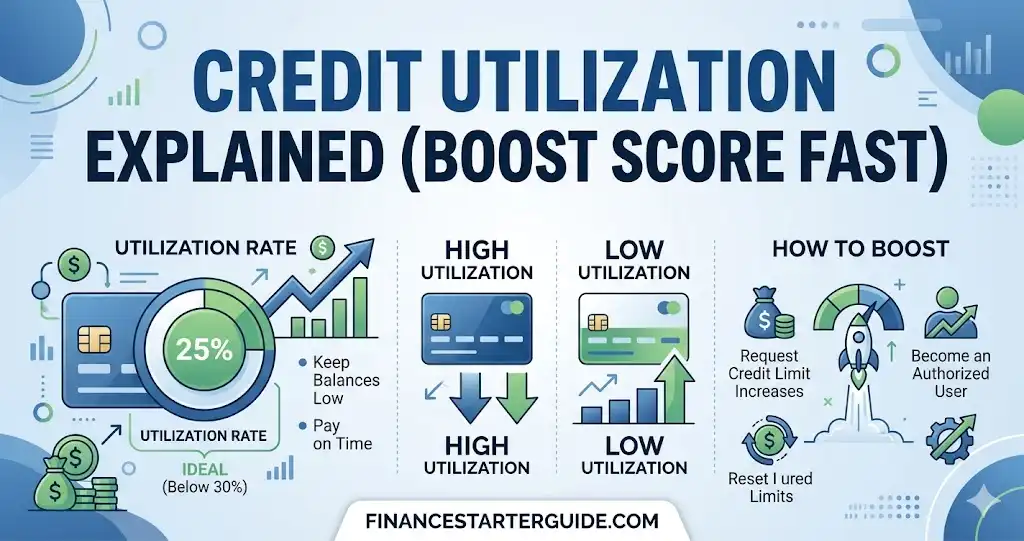
Ideally, the amount you obtain must be less than 30% of your readily available credit limitation. This is called your credit usage rate. So, if you have a card with a $5,000 limit, 30% of that is $1,500. But to me, the best guide is to only charge what you can pay off each monththat ought to be your real limit.
This will assist you construct credit and, at the exact same time, stay out of financial obligation. New accounts and several credit applications can lower your score and cause loan providers to see you as a greater threat. Many cards provide rewards and discount rates to lure you in, but do not be lured by totally free things.
Effective Methods for Repairing Your Credit Quickly
That $10 off now could end up costing you a lot more later on. And while it may appear counterproductive, each time you apply for a new credit card, the lending institution will usually run a "difficult inquiry" into your credit historyand credit queries can result in negative marks on your credit rating.
Your credit mix matters. In addition to charge card, having other types of credit such as student loans, an auto loan, or a mortgage can enhance your score. Avoid opening brand-new accounts simply to assist your credit score. It's better to establish the discipline of paying for financial obligation and handling your current credit wisely.
This consists of accounts you no longer use and those with a no balance. As long as they're open, they will be factored into the average age of your credit. You don't have to bring a balance to help your credit history. However, a word of caution here too: Do not be lured to utilize a credit card even if it's there.

Latest Posts
Methods to Increase Credit Score Fast 2026
Effective Strategies for Fixing Poor Credit Quickly

Locating Free Credit Counseling Near Me in 2026