All Categories
Featured

Efficient Ways to Conflict Credit Errors in 2026
Table of Contents
- – Improving Credit Precision in 2026
- – Particular Patterns for Credit Repair Solution...
- – Fact-Based Disagreement Documentation
- – The Function of Alternative Data in 2026
- – Strategies for Financial Institution Direct-Ne...
- – Determining Typical Reporting Discrepancies
- – Keeping Progress and Future-Proofing Credit
- – Last Thoughts on Credit Management

Improving Credit Precision in 2026
The shift towards automated data processing has reached a new peak in 2026, forcing a modification in how consumers approach their financial records. For many years, individuals count on generic template letters to challenge mistakes on their reports. In the present year, those techniques seldom set off a manual review. The three significant credit bureaus now use innovative device discovering systems that can identify and dismiss boiler-plate templates within seconds. Expert monetary therapists highlight that successful conflicts now require a more surgical technique based upon factual information points rather than vague legal claims.Accuracy in 2026 is no longer almost getting rid of unfavorable marks. It is about ensuring every detail-- from work history to the exact date of a last payment-- lines up throughout all 3 significant reporting agencies. Mistakes often take place when creditors use different software application variations to publish information. These technical disparities create "fragmented files" that can lower a credit rating even if the payment history is perfect. Attending to these fragments requires an understanding of how information flows from the creditor to the repository.
Particular Patterns for Credit Repair Solutions in Tennessee
Locals looking for a better monetary standing have actually found that localized information trends matter. In Tennessee, specific local loan providers have transitioned to real-time reporting designs. While this assists those who pay on time see instant score boosts, it likewise suggests that any clerical mistake by a regional branch appears on a report practically quickly. High-level therapy focuses on determining these real-time reporting lags. Success typically stems from knowledge in Credit Disputes during the examination phase. By identifying the specific moment an information package was misidentified, customers can require a correction much faster than the standard thirty-day window.Professional strategies in 2026 also focus on the "City 2" format. This is the basic language utilized by lenders to communicate with bureaus. A lot of consumers are unaware that a conflict is most reliable when it highlights a City 2 field error. If a lender reports a "Date of Last Activity" that does not match the "Date of First Delinquency" according to the particular code needed by the bureau, the account needs to be remedied. Financial consultants in Tennessee invest substantial time auditing these codes to discover inconsistencies that the typical individual would ignore.
Fact-Based Disagreement Documentation

The days of simply mentioning "this is not mine" are gone. In 2026, the concern of evidence has moved a little due to the E-OSCAR (Electronic Online System for Total and Precise Reporting) updates. Lenders now have access to digital "image repositories" where they can quickly pull a signed contract or a payment scan to validate an account. To win a disagreement, a customer must supply proof that is equally digital and verifiable. This might include bank statements showing a cleared check that was never credited or a letter from an insurance provider confirming a medical bill was paid.Increased interest in Proactive Spending Realignment Steps shows a wider shift towards information precision. When a conflict is filed, it is assigned a four-digit code by the bureau's AI. If the code is "001" (Not Mine), the system carries out an easy name and address match. If the consumer offers a particular "002" (Account Not Joint) or "012" (Claims Account Closed) with supporting documentation, the system is forced to route the file to a human investigator. This human touch is where most professional counselors find their triumphes.
The Function of Alternative Data in 2026
Credit building in 2026 has broadened far beyond charge card and car loans. Many bureaus now consist of "Level 2" information, which consists of rent payments, utility costs, and even membership services. This is a double-edged sword. While it supplies more methods to build a favorable history, it likewise introduces more chances for reporting mistakes. A missed out on garbage collection charge in Tennessee might possibly appear as a collection account if the company utilizes a third-party billing agency.Counselors suggest that customers routinely examine their "secondary" reports. These are smaller, specialized reporting agencies that track occupant history and check-writing practices. Typically, a mistake on a main credit report stems from among these smaller databases. Correcting the source is often much easier than combating the main bureau, as the smaller sized firms have less automatic defenses and are more responsive to direct queries.
Strategies for Financial Institution Direct-Negotiation
Sometimes the most reliable method to manage a conflict is to bypass the bureaus entirely. In 2026, "Goodwill Removals" have been mostly replaced by "Accuracy Adjustments." Big banks and credit unions in Tennessee have actually dedicated departments for information stability. If a customer can show that a late payment was brought on by a technical problem on the bank's mobile app or an interruption in the local banking network, these departments can upgrade the internal record. When the internal record is repaired, the update naturally streams to the credit bureaus during the next reporting cycle.This technique requires persistence and a clear proof. It is useful to tape-record the dates and times of technical issues or to keep screenshots of payment confirmation screens. Individuals often try to find Credit Disputes for Consumer Protection to resolve persistent reporting errors that the bureaus refuse to acknowledge. By dealing straight with the source, the customer eliminates the middleman and addresses the root of the issue.
Determining Typical Reporting Discrepancies
Information entry remains a human process at some level, and errors are inescapable. In 2026, common errors consist of:.
- Duplicate accounts where a financial obligation was sold to a brand-new collector but the original financial institution failed to upgrade the balance to zero.
- Inaccurate credit limitations that make a consumer's usage look greater than it really is.
- Mixed files where data from two people with comparable names or social security numbers are integrated.
- Re-aging of old financial obligations, which takes place when a collection firm incorrectly alters the "date of very first delinquency" to keep an unfavorable product on the report longer than seven years.
Each of these errors requires a specific legal citation under the FCRA. Writing a letter that points out Section 611 or Section 623 specifically signals to the bureau that the customer understands their rights. This frequently leads to a more thorough examination than a letter that simply requests for "assistance" or "removal.".
Keeping Progress and Future-Proofing Credit
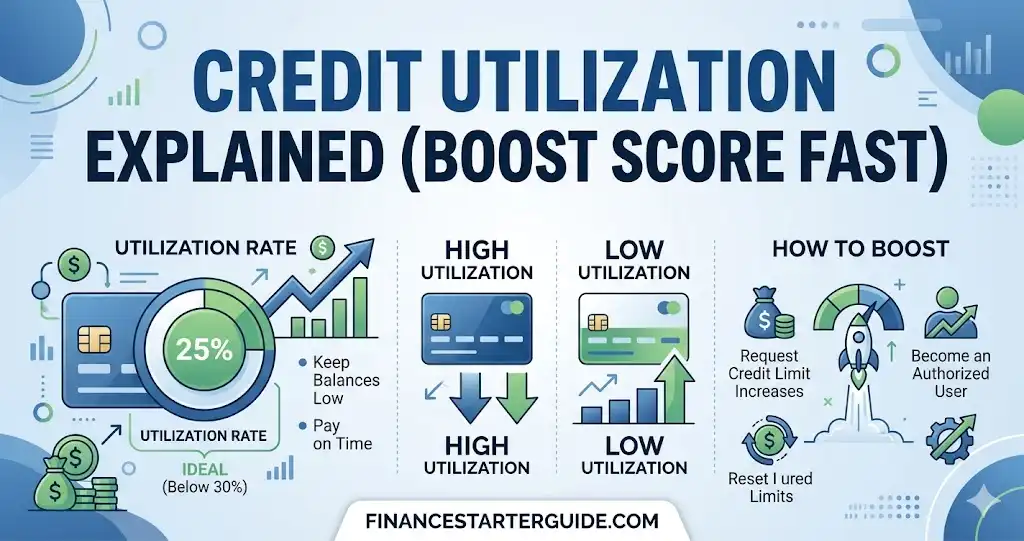
Once a conflict is successful, the work is not ended up. The credit environment of 2026 moves rapidly. A deleted item can often "re-pollute" a report if the financial institution's software application is not updated. Tracking services are vital for capturing these "zombie" accounts before they cause substantial damage. Professional financial counseling typically consists of a three-to-six month follow-up duration to guarantee that remedied products stay corrected.Building credit in 2026 also involves tactical debt management. Counselors recommend keeping credit utilization below 7 percent, a much lower threshold than the 30 percent recommended in previous years. This change is because of the increased level of sensitivity of the current scoring algorithms. High-limit cards need to be utilized moderately, and balances must be settled multiple times a month to make sure the reported balance is always at its lowest point.
Last Thoughts on Credit Management
The path to an ideal rating in Tennessee includes a mix of technical understanding and relentless follow-up. While the innovation used by bureaus has actually ended up being more complex, the underlying principle remains the exact same: the law needs one hundred percent accuracy. Whether an individual is using a professional advisor or browsing the procedure alone, success pertains to those who document every action and understand the digital systems behind the numbers. In 2026, the most effective tool a customer has is not simply the law, but the data that shows their financial story is being told correctly. Trustworthy credit is the structure of contemporary life, and keeping that foundation solid needs constant watchfulness and an eye for information.

Table of Contents
- – Improving Credit Precision in 2026
- – Particular Patterns for Credit Repair Solution...
- – Fact-Based Disagreement Documentation
- – The Function of Alternative Data in 2026
- – Strategies for Financial Institution Direct-Ne...
- – Determining Typical Reporting Discrepancies
- – Keeping Progress and Future-Proofing Credit
- – Last Thoughts on Credit Management
Latest Posts
Methods to Increase Credit Score Fast 2026
Effective Strategies for Fixing Poor Credit Quickly

Locating Free Credit Counseling Near Me in 2026
Latest Posts
Methods to Increase Credit Score Fast 2026
Effective Strategies for Fixing Poor Credit Quickly
Locating Free Credit Counseling Near Me in 2026