All Categories
Featured


Proven Tips to Boost Your Credit Rating Quickly
A bipartisan group of lawmakers has introduced legislation to crack down on deceptive practices utilized by fraudulent credit repair organizations.The Ending Fraud Credit Repair Act, or ESCRA, by Sens. Chris Coons( D-Del. )and Lisa Murkowski( R-Alaska) would reinforce defenses for consumers by restricting credit repair work companies from collecting payment up until 6 months after they have provided evidence that a customer's credit history has actually improved, according to the sponsors. A companion expense( H.R. 306) was presented in your house by Reps. Sarah McBride( D-Del.) and Young Kim( R-Calif. ). In a declaration in assistance of the legislation, Kirsten Sutton, EVP of congressional relations and legislative affairs at the American Bankers Association, kept in mind that banks assist customers build credit through transparent items, financial education and long-lasting support, "and this important legislation strengthens those responsible paths by targeting deceptive credit repair plans."" ABA has consistently supported efforts to strengthen consumer self-confidence in the credit system, and we applaud Senators Coons and Murkowski, and Representatives McBride and Kim, for their management in working to make sure consumers are secured, "Sutton stated. The campaign will gear up both customers and bank volunteers with dependable info, useful tools and professional insights, including advice on how to identify deceptive credit repair companies.( Article Updated Jan. 6 and 8, 2026) This article notes federal and state customer law modifications arranged to enter into impact or expire during the period from December 1, 2025, through January 1, 2027. Other customer law changes will be enacted in 2026 and will enter into impact in 2026; this post lists changes whose reliable dates have actually currently been set up since December 31, 2025. NCLC motivates readers to send( to) extra consumer law changes effective in 2026, particularly modifications in state customer legislation. NCLC will include appropriate submissions to this short article. Important modifications to Bankruptcy Rule 3002.1 and 6 associated new insolvency types entered into effect on December 1, 2025. The changes safeguard homeowners who use chapter 13 bankruptcies to stave off foreclosures and keep themselves current on their home loans, providing information needed to effectively finish a treatment strategy and emerge from chapter 13 without surprise, undisclosed fees, or payment amounts due. New Rule 8006( g) will clarify that any party to an appeal might file a demand that a court of appeals authorize a direct appeal. 26 U.S.C. 108( a) supplies that specific forgiveness on a home loan is not thought about earnings for income tax functions, however the Qualified Principal Residence Indebtedness Exemption from Income expired at the end of 2025. Although other exclusions from taxability of forgiven financial obligation might use, this exclusion no longer uses. The American Rescue Strategy Act momentarily eliminated federal income tax repercussions for all federal trainee loan discharges and cancellations that happened between January 1, 2021, and December 31, 2025. See. This exemption has actually not been extended, and the amounts released or cancelled from federal trainee loans beginning on January 1, 2026, may count toward taxable income unless another exclusion uses. See( Dec. 15, 2025 ). This exemption does not use to home-secured credit or student loans. See. On January 1, the adjusted overall loan amount threshold for high-cost home mortgages increases from $26,968 to$ 27,592, and the changed points and costs dollar trigger for high-cost home mortgages increases from$ 1,348 to $1,380. 15, 2025 ). See. To identify whether a covered transaction is a competent home mortgage( QM), the total points and costs charged might not go beyond the threshold set for the size of the loan. Reliable January 1, 2026, these limits increase. For QMs under the basic QM loan definition in 12 C.F.R. For all classifications of QMs, the thresholds for overall points and charges in 2026 will be 3% of the total loan quantity for a loan greater than or equal to$ 137,958;$ 4,139 for a loan amount greater than or equivalent to$ 82,775 however less than$ 137,958 ; 5% of the total loan amount for a loan greater than or equal to$ 27,592 however less than$ 82,775;$ 1,380 for a loan quantity greater than or equal to $17,245 however less than $27,592; and 8% of the total loan quantity for a loan quantity less than $17,245. 15, 2025 ). See generally. Effective January 1, the exemption threshold for special appraisal requirements for "higher-risk home mortgages "increases from $33,500 to $ 34,200. See (Dec. 16, 2025). See also. Truth in Lending Reg. Z, 12 C.F.R. 1026.6 (b) (2)( iii )and 1026.60( b)( 3) require financial institutions to divulge any minimum interest charge surpassing $1.00 that might be imposed throughout a billing cycle. 7, 2026). Efficient January 1, 2026, banks, cost savings associations, and cooperative credit union with possessions of $59 million or less since Dec. 31, 2025, are exempt from collecting data in 2025( the old threshold was $58 million ).( Jan. 7, 2026). The CRA property thresholds for specific exemptions are increased as of January 1, 2026, so that "small bank "suggests a bank that, as of December 31 of either of the prior two fiscal year, had possessions of less than$ 1.649 billion. See( Jan. 7, 2026). Efficient January 1, 2026, the maximum charge to a consumer under the FCRA for file disclosure is$ 16.00, up from$ 15.50. (Dec. 15, 2025 ). Consumers are also entitled to particular complimentary disclosures, including totally free weekly file disclosures from Equifax, Experian, and TransUnion. See. On January 1, 2026, the Customer Leasing Act exemption for customer leases surpassing a total legal obligation amount is increased from$ 71,900 to$ 73,400. 15, 2025). See. FHA has revealed new loan limits for 2026. The single-family, low-cost-area ceiling increases to $541,287 and the high-cost-area ceiling increases to$ 1,249,125. See( Dec. 11, 2025). For HECM reverse home mortgages the maximum claim amount increases on January 1 to $1,249,125. See (Dec. 11, 2025). Theconforming loan limitations for 2026 for Fannie Mae and Freddie Mac home mortgages. In the majority of the United States, the 2026 value for 1-unit properties will be$ 832,750. For areas in which 115% of the regional median home worth exceeds the baseline conforming loan limitation worth, the relevant loan limit for 1-unit properties will be$ 1,249,125.
Arizona has a new lawsuits funding statute,, reliable January 1 2026. needs self-storage rental agreements at first participated in on or after January 1, 2026, to divulge, in a prescribed way, whether the rental cost is discounted or promotional, whether the rental cost undergoes change, and the maximum rental cost that.
the owner might charge throughout the first 12 months following the date of the rental contract., efficient January 1, 2026, requires a social media platform to provide a clear and noticeable button that makes it possible for the user to delete their account and offer the user with the required actions to delete the user's account and personal info. The costs forbids a social.
How to Raise Your Credit Score for 2026media platform from blocking or interfering with a user's capability to delete their account., effective January 1, 2026, loosens proof requirements for a cost fixing claim under state law and forbids usage or circulation of a common rates algorithm as part of a cost fixing scheme. also significantly increases civil and criminal penalties for infractions of the state anti-trust law.

2026 Credit Laws and Your Score Impact
Georgia has a brand-new lawsuits funding statute,, managing foreign third-party litigation funders that goes into effect on January 1, 2026., efficient January 1, 2026, offers various protections for domestic partners whose partner persuades them to take on debt, whether by force or fraud. Efficient January 1, 2026, offers that in the case of a consumer customer financial obligation entered gotten in or after January 1, 2020,$ 1,000 of the$ 4,000 wild card is automatically instantly to the judgment debtor's interest in a checking or savings cost savings account. Starting January 1, 2026, the base optimum cost is adjusted each year to the lesser of (1)$ 425, adjusted by inflation or( 2) the quantity resulting from applying a development rate of three percent to the adjusted optimum fee for the previous calendar year.

Latest Posts
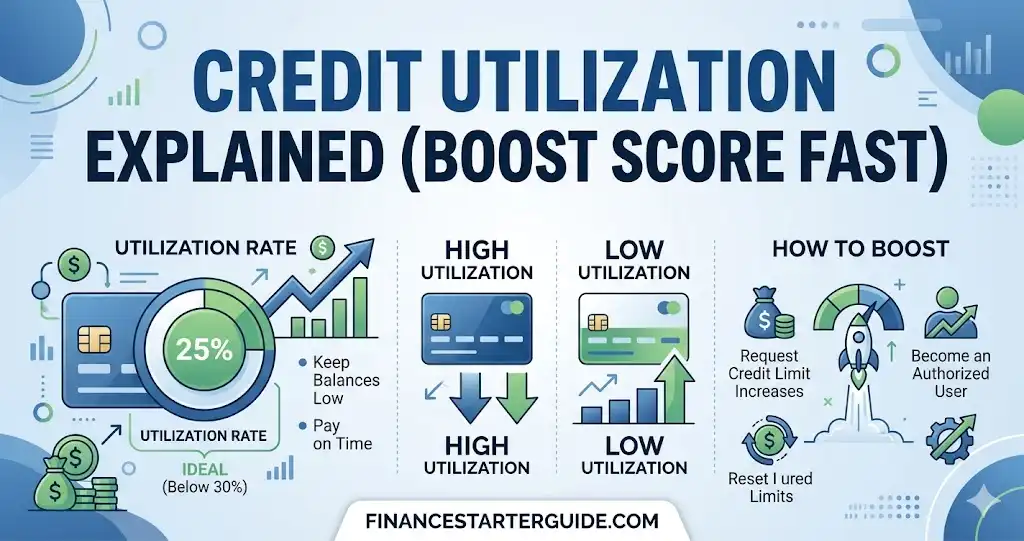
Methods to Increase Credit Score Fast 2026
Effective Strategies for Fixing Poor Credit Quickly

Locating Free Credit Counseling Near Me in 2026