All Categories
Featured

The Link Between Debt and Property Growth
Table of Contents
Modernizing Credit Healing in Colorado
Financial recovery in 2026 requires more than easy patience and automated payments. The economic environment has moved toward data-heavy examination, where loan providers look beyond a single score to examine how people manage their month-to-month obligations. For homeowners who have faced abrupt earnings loss or unexpected expenses, the course to a higher credit ranking includes a mix of technical corrections and behavioral changes.Credit scoring models in 2026 prioritize trended information. This indicates the last 24 months of payment history carry more weight than older errors. Somebody living in Colorado might discover that while a major obstacle from two years ago still appears on their report, current constant behavior can considerably offset its impact. Financial counselors now emphasize the "velocity of repair work," which focuses on how rapidly a consumer go back to a status of on-time payments after a duration of delinquency.Accuracy is the first pillar of any recovery plan. It prevails for credit reports to include clerical errors or out-of-date collection statuses. Verification stays the most direct method to see an immediate bump in a score. Numerous people discover that results through Payoff Calculators supply the needed clearness to move on with a conflict or a formal correction request. Clearing up a single misreported late payment can in some cases move a rating from the subprime category into a more beneficial tier.
Strategic Use of Debt
Expert assistance has actually ended up being a standard part of the restoring process in 2026. Rather than browsing complex laws alone, lots of consumers turn to specialized services to deal with the communication with bureaus and lenders. Utilizing Debt allows for a more structured approach to debt validation. This is especially useful when handling "zombie debt" or old accounts that have been offered numerous times in between collection agencies.Expert counselors often suggest the "reporting growth" technique. In 2026, lots of scoring designs now accept "alternative data," that includes utility bills, streaming subscriptions, and lease payments. Previously, these expenses did not assist a credit score. Now, they are frequently the fastest way to construct a "thin file" into a more considerable history. For those in Colorado, opting into these reporting programs can reveal a pattern of reliability that conventional credit cards might miss.Security is likewise a major issue. When restoring, customers are frequently targets for high-interest predatory loans. Expert therapists caution against "credit repair" plans that assure to wipe a report clean overnight. Real development is determined in months, not days. The advantages of Emerging Fintech Financial Risks are found in long-term strategy and the education offered to the consumer, instead of quick-fix gimmicks that may breach federal policies.
Managing High-Interest Responsibilities and Collections
The high rates of interest environment of 2026 makes bring revolving debt pricey. If a customer is stuck with a charge card balance at a 28% rates of interest, the interest alone can avoid the principal from ever decreasing. Debt restructuring is frequently a better course than simple minimum payments. Negotiating a "pay-for-delete" agreement with a debt collection agency is one strategy that has seen a renewal in 2026. In this situation, the customer accepts pay a portion of the financial obligation in exchange for the firm eliminating the unfavorable entry entirely.However, these contracts need to remain in composing. Verifying that a debt collector has the legal right to collect is the primary step. If a financial obligation is beyond the statute of restrictions for Colorado, paying it could in fact reboot the clock on the length of time it remains on the report. Understanding these particular legal timelines is a trademark of expert counseling techniques used today.
New Credit Building Tools for 2026
Standard charge card are no longer the only way to develop a positive history. Protected cards stay popular, however "credit contractor loans" have become more advanced. These products work by holding the loan amount in a locked savings account while the consumer makes month-to-month payments. As soon as the loan is settled, the funds are launched to the customer, and the history of on-time payments is reported to all three major bureaus.Another trend in 2026 is making use of fintech platforms that use "margin-based" credit. These accounts look at a person's bank balance and earnings instead of simply their previous credit history. By revealing a constant money circulation, people can access little lines of credit that help develop a score without the risk of deep financial obligation. Those researching Financial Psychology for Borrowers typically discover that these tech-forward options provide a bridge when standard banks offer restricted alternatives.
The Effect of Medical Debt and Public Records
A significant modification in 2026 is how medical financial obligation is dealt with. The majority of medical collections under a certain limit no longer appear on credit reports, and paid medical debt is removed instantly. This has provided relief for countless individuals whose scores were previously suppressed by health care costs. Tax liens and civil judgments can still create obstacles.Counselors in Colorado recommend a "clean slate" audit every 6 months. This involves checking for any public records that may have been settled but not yet upgraded in the bureau's database. Due to the fact that much of the credit reporting process is now automated through AI, little data inequalities can result in considerable score drops. Keeping a proof of every settlement and payment is more vital now than it was five years ago.
Developing Sustainable Financial Habits
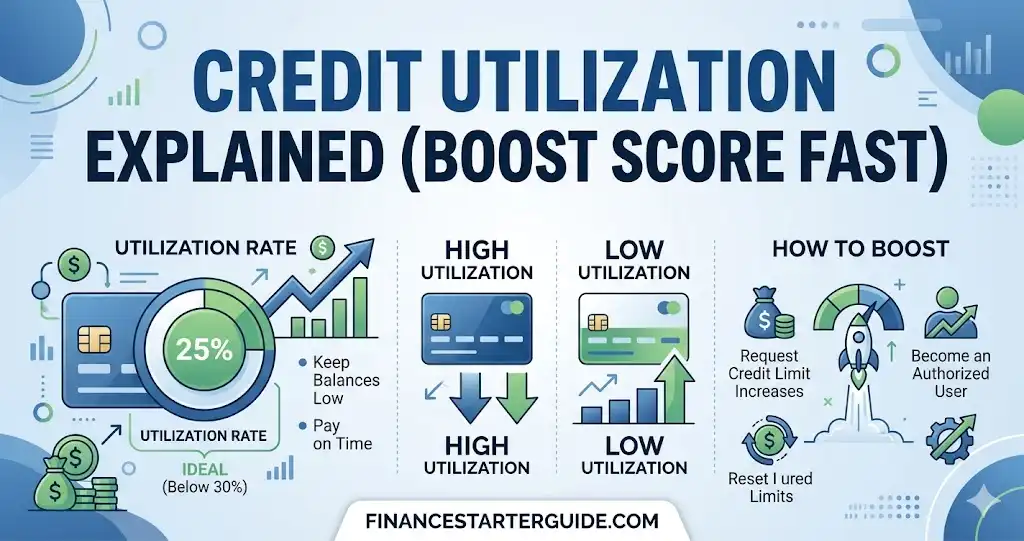
Restoring is not just about the numbers; it has to do with altering the underlying habits that caused the setback. Budgeting apps that sync directly with checking account have actually become more predictive. In 2026, much of these tools can alert a user if their existing costs will lead to a missed out on payment 3 weeks before the due date. This proactive technique assists avoid new damage while old damage is being repaired.Setting up a "buffer fund" is the very best defense versus future credit hits. Many professionals recommend a minimum of one month of expenditures in a liquid account. When a vehicle repair work or medical bill occurs, the customer can pay in cash instead of counting on high-interest credit, which protects the utilization ratio. Credit utilization-- the amount of credit utilized versus the overall limit-- stays a heavy aspect in scoring. Keeping this under 10% is the objective for anybody severe about reaching the top-tier score brackets.
Last Steps in the Rebuilding Process
Once a score begins to climb up, the temptation to use for multiple new accounts is high. Nevertheless, "tough questions" can briefly decrease a rating. In 2026, lending institutions are more conscious "credit seeking habits." It is much better to wait for pre-approved deals with beneficial terms than to shotgun applications across different lenders.Consistency over a 12-month period is normally adequate to move a rating from "poor" to "fair" or "excellent." For a local of Colorado, this development opens doors to lower insurance coverage premiums, better rental alternatives, and enhanced home mortgage rates. The financial landscape of 2026 is competitive, and a healthy credit profile is the most valuable tool a consumer can own. By combining professional Debt with modern-day fintech tools and disciplined spending, anybody can overcome a financial setback and restore their standing in the market.The procedure is often slow, but the cumulative effect of little, right actions is effective. Each on-time payment and each challenged error brings the customer more detailed to a state of monetary freedom where they are no longer defined by their past mistakes. Staying notified about modifications in credit laws and scoring models will ensure that the progress made in 2026 lasts for years to come.

Latest Posts
Methods to Increase Credit Score Fast 2026
Effective Strategies for Fixing Poor Credit Quickly

Locating Free Credit Counseling Near Me in 2026